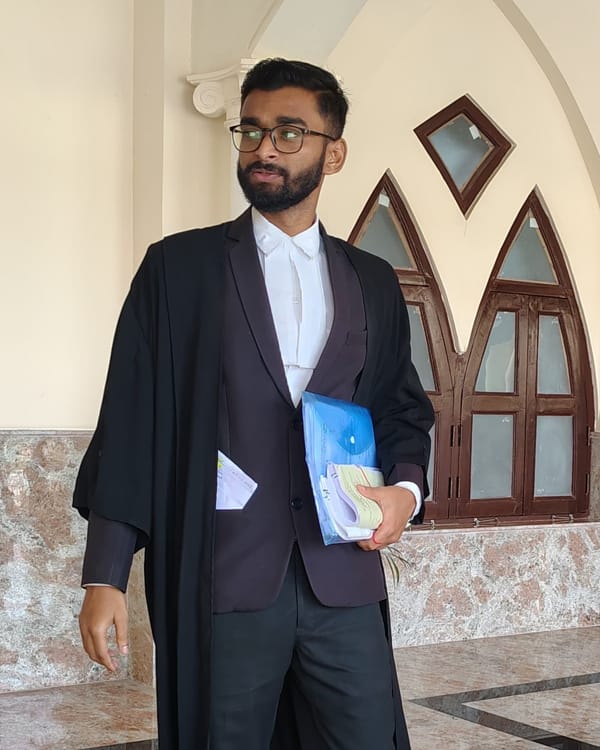
GST Lawyer in Jalpaiguri
Satyajit Paul, Advocate · Calcutta High Court, Circuit Bench at Jalpaiguri
Satyajit Paul appears in Goods and Services Tax disputes of traders, manufacturers and service providers from Jalpaiguri, Siliguri and the rest of North Bengal. This page explains, in general terms, how GST registration disputes, demand notices, appeals, the GST Appellate Tribunal and writ petitions work, and lists the matters in which he accepts briefs.
This page is general legal information published in keeping with Bar Council of India rules, which permit an advocate's website to state his areas of practice. It is not legal or tax advice and does not create a lawyer-client relationship. References are to the Central Goods and Services Tax Act, 2017 ("CGST Act"); the West Bengal Goods and Services Tax Act, 2017 has matching sections. The position is stated as of October 2026.
GST matters handled
Satyajit Paul is enrolled with the Bar Council of West Bengal and practises at the Calcutta High Court, Circuit Bench at Jalpaiguri. Monthly returns, reconciliations and day-to-day compliance are usually handled by a chartered accountant or GST practitioner; someone searching for a "GST consultant in Siliguri" for filing returns needs that kind of help. Where a dispute arises with the department, he accepts briefs in the following matters:
- Refusal, suspension and cancellation of GST registration, and applications for revocation
- Replies to show-cause notices under sections 73, 74 and 74A of the CGST Act
- Disputes over input tax credit, including credit denied because of a supplier's default
- Appeals to the Appellate Authority under section 107
- Appeals to the Goods and Services Tax Appellate Tribunal under section 112
- Writ petitions under Article 226 against orders passed without a hearing, without jurisdiction or out of time, and against bank attachment
- Detention and seizure of goods in transit, and e-way bill disputes
- Defence in proceedings for arrest and prosecution under sections 69 and 132
Registration, suspension and cancellation
A supplier must register under section 22 of the CGST Act once aggregate turnover crosses the threshold for the State, and certain persons, such as inter-State suppliers of goods and e-commerce operators, must register under section 24 regardless of turnover. An application is made under section 25 and verified by the officer, who may ask for clarification or physical verification of the place of business.
Registration disputes are common and serious, because without a valid GSTIN a business cannot issue tax invoices and its buyers cannot take credit:
- Rejection of an application must be preceded by a notice and an opportunity to reply.
- Suspension may be ordered while cancellation proceedings are pending, for example where returns show significant differences from supplier data.
- Cancellation under section 29 may follow failure to file returns for a specified period, a business not being carried on at the declared place, or registration obtained by fraud. A show-cause notice and hearing are required, and the order must give reasons. Cancellation can be made retrospective, which may reverse the credit taken by customers, so a retrospective order without reasons is open to challenge.
- Revocation of cancellation can be applied for under section 30 within the time allowed by the rules, and a refusal can be taken in appeal under section 107.
Show-cause notices and demands: sections 73, 74 and 74A
Where tax has not been paid or has been short-paid, or input tax credit has been wrongly taken or utilised, or a refund has been wrongly granted, the proper officer issues a show-cause notice. Which section applies depends on the financial year involved.
| Provision | Applies to | Time limits | Penalty |
|---|---|---|---|
| Section 73 (no fraud or suppression) | Financial years up to 2023-24 | Order within three years from the due date of the annual return; notice at least three months before that | 10 per cent of the tax or ₹10,000, whichever is higher |
| Section 74 (fraud, wilful misstatement or suppression) | Financial years up to 2023-24 | Order within five years from the due date of the annual return; notice at least six months before that | Equal to the tax, reduced if tax, interest and penalty are paid at earlier stages |
| Section 74A (both kinds of case) | Financial year 2024-25 onwards | Notice within 42 months from the due date of the annual return (or of an erroneous refund); order within 12 months of the notice, extendable by up to six months | Non-fraud: 10 per cent of the tax or ₹10,000, whichever is higher. Fraud or suppression: equal to the tax, reduced for early payment |
Section 74A was inserted by the Finance (No. 2) Act, 2024. It uses a single time limit for both kinds of case, so the question of whether fraud is alleged now affects mainly the penalty, not the period of limitation. No notice is to be issued under section 74A where the tax involved is less than one thousand rupees.
Before a formal notice the officer may communicate the proposed liability in Form GST DRC-01A (pre-show-cause intimation) and allow voluntary payment. Paying tax with interest at that stage, where the liability is accepted, can avoid or reduce penalty. Where it is disputed, the objection should be recorded in writing.
Replying to a notice and the right to a hearing
The reply to a show-cause notice is the most important document in a GST dispute. It should deal with every allegation, attach the supporting invoices, e-way bills, bank records and reconciliations, and raise legal objections such as limitation, absence of any allegation of fraud in a section 74 notice, or a demand made without examining the documents already filed.
Under section 75(4) of the CGST Act an opportunity of personal hearing must be given where the person asks for one in writing, or where any adverse decision is contemplated. The order must not travel beyond the grounds in the notice, and the amount demanded cannot exceed the amount specified in it (section 75(7)). Many orders uploaded on the GST portal have been set aside by the High Courts because no hearing was given, the reply was not considered, or the notice was only uploaded under a tab the taxpayer could not reasonably be expected to see.
First appeal under section 107
An order passed by an adjudicating authority is appealed to the Appellate Authority (for orders of State officers, the Additional or Joint Commissioner (Appeals) of the State tax department; for orders of central officers, the Commissioner (Appeals) of central tax).
- Time limit: three months from the date the order is communicated, with up to one further month if sufficient cause is shown. The Appellate Authority cannot condone delay beyond that.
- Pre-deposit: the admitted tax, interest and penalty in full, plus 10 per cent of the tax in dispute, subject to the maximum fixed by section 107(6). On payment of the pre-deposit, recovery of the balance is stayed until the appeal is decided.
- Filing: online in Form GST APL-01, with the order and grounds of appeal, followed by a certified copy where required.
- Hearing and order: the Appellate Authority must hear the appellant and may confirm, modify or annul the order, but cannot send the case back to the original authority for fresh adjudication.
The GST Appellate Tribunal: status as of October 2026
For years the Tribunal existed only on paper, and taxpayers whose first appeal failed had no second appeal to file, which pushed many cases into the High Courts by writ. That has changed. The Goods and Services Tax Appellate Tribunal (GSTAT) has been constituted, its online filing portal is working, and State benches have begun to sit. The Kolkata Bench, which covers West Bengal, Sikkim and the Andaman and Nicobar Islands, began functioning on 23 March 2026. Appeals from Jalpaiguri, Siliguri and the rest of North Bengal therefore go to the Kolkata Bench.
- Backlog appeals: for orders of the Appellate Authority communicated before 1 April 2026, the Central Government fixed a single outer date for filing, first 30 June 2026 and then extended to 31 July 2026. That window has now closed; a late appeal needs an application for condonation of delay.
- New appeals: an order communicated on or after 1 April 2026 may be appealed within three months under section 112, and the Tribunal may admit an appeal within a further three months for sufficient cause.
- Pre-deposit: a further 10 per cent of the tax in dispute, in addition to the amount paid at the first appeal, subject to the statutory maximum.
Against an order of the Tribunal, an appeal lies to the High Court under section 117 where the case involves a substantial question of law, and to the Supreme Court under section 118.
Writ petitions in GST matters
The existence of an appeal ordinarily leads the High Court to decline a writ petition. The Court will, however, intervene under Article 226 where an order is passed without jurisdiction or after the limitation period, in breach of natural justice (no hearing, reply ignored, reasons absent), or where a provision or notification is challenged as unconstitutional. Writs are also filed where a bank account is provisionally attached under section 83 without the conditions being met, or where registration is cancelled retrospectively without reasons.
The Calcutta High Court hears GST writs arising in West Bengal. Where the order is passed by an officer or the cause of action arises within Darjeeling (including Siliguri), Kalimpong, Jalpaiguri, Alipurduar or Cooch Behar, the petition can be filed at the Circuit Bench at Jalpaiguri. Now that the Tribunal is sitting, the High Court is likely to expect a statutory appeal to be filed where it is available, so a writ should be reserved for cases that genuinely fall within the exceptions.
Documents usually needed
- The notice, intimation (DRC-01A), show-cause notice (DRC-01) or order (DRC-07) under challenge, with the date it was uploaded or served
- GSTR-1, GSTR-3B and annual returns for the period, and GSTR-2A/2B statements
- Purchase and sale invoices, e-way bills and transport documents for the transactions questioned
- Bank statements showing payment to suppliers, where input tax credit is disputed
- Registration certificate, and any notice or order of suspension or cancellation
- All earlier replies, hearing notices and acknowledgements
- For an appeal: proof of pre-deposit (payment through the electronic cash or credit ledger)
Frequently asked questions
What is the difference between sections 73, 74 and 74A of the CGST Act?
Sections 73 and 74 apply to demands for financial years up to 2023-24: section 73 where there is no fraud or suppression (order within three years of the annual return due date) and section 74 where fraud or wilful suppression is alleged (five years). Section 74A, inserted by the Finance (No. 2) Act, 2024, applies from financial year 2024-25 to both kinds of case, with a single 42-month limit for the notice and a 12-month limit (extendable by six months) for the order. The penalty still depends on whether fraud is alleged.
How long do I have to file a GST appeal?
An appeal to the Appellate Authority under section 107 must be filed within three months of the order being communicated, extendable by one month for sufficient cause. An appeal to the GST Appellate Tribunal under section 112 must be filed within three months of the appellate order, and the Tribunal may admit it within a further three months if there is sufficient cause.
Is the GST Appellate Tribunal working now?
Yes. The Tribunal's Kolkata Bench, covering West Bengal, Sikkim and the Andaman and Nicobar Islands, began functioning on 23 March 2026. Backlog appeals against orders communicated before 1 April 2026 had to be filed by 31 July 2026; later orders follow the normal three-month limit.
How much must be deposited to file a GST appeal?
For the first appeal, the admitted amount in full plus 10 per cent of the disputed tax, subject to the ceiling in section 107(6). For the Tribunal, a further 10 per cent of the disputed tax, in addition to the first deposit, subject to the ceiling in section 112(8). Once the pre-deposit is paid, recovery of the rest of the demand is stayed while the appeal is pending.
My GST registration has been cancelled. What can be done?
If cancellation was for non-filing of returns, the pending returns can be filed and an application for revocation made under section 30 within the time allowed. If revocation is refused, or the cancellation was on other grounds, an appeal lies under section 107. Where the cancellation was made retrospective without reasons or without a hearing, a writ petition before the High Court may be appropriate.
Can I go to the High Court instead of filing a GST appeal?
Generally only in exceptional cases: where the order is without jurisdiction or time-barred, where no hearing was given or the reply was ignored, or where a provision is challenged as unconstitutional. With the Tribunal now functioning, the High Court is more likely to direct taxpayers to the appeal remedy. For the five North Bengal districts, GST writs can be filed at the Calcutta High Court's Circuit Bench at Jalpaiguri.
My input tax credit was denied because my supplier did not pay tax. Can that be challenged?
Section 16 of the CGST Act makes credit conditional on, among other things, the tax having been paid to the Government. Purchasers have challenged denial of credit where they paid the supplier in full, hold valid invoices and the goods were actually received. Whether such a challenge can succeed depends on the evidence of a genuine transaction, so invoices, e-way bills, transport records and bank payments should be kept together.
The answers above describe the law in general terms as on the date of publication and may not reflect later amendments or judgments. They are not a substitute for advice on the facts of a particular case.
Contact
Chamber at Santipara Bus Stand, Jalpaiguri, West Bengal 735101. Monday to Saturday, 10:00 to 22:00, by appointment. English, Bengali and Hindi.